Generates random deviates from the Beta-Kumaraswamy (BKw) distribution
with parameters alpha (\(\alpha\)), beta (\(\beta\)),
gamma (\(\gamma\)), and delta (\(\delta\)). This distribution
is a special case of the Generalized Kumaraswamy (GKw) distribution where
the parameter \(\lambda = 1\).
Arguments
- n
Number of observations. If
length(n) > 1, the length is taken to be the number required. Must be a non-negative integer.- alpha
Shape parameter
alpha> 0. Can be a scalar or a vector. Default: 1.0.- beta
Shape parameter
beta> 0. Can be a scalar or a vector. Default: 1.0.- gamma
Shape parameter
gamma> 0. Can be a scalar or a vector. Default: 1.0.- delta
Shape parameter
delta>= 0. Can be a scalar or a vector. Default: 0.0.
Value
A vector of length n containing random deviates from the BKw
distribution. The length of the result is determined by n and the
recycling rule applied to the parameters (alpha, beta,
gamma, delta). An out-of-bound or missing parameter is an
error, not a return value: the wrapper stops with a message naming the
parameter. An infinite parameter is not currently intercepted there and
reaches the C++ layer, which treats it as invalid.
Details
The generation method uses the relationship between the GKw distribution and the
Beta distribution. The general procedure for GKw (rgkw) is:
If \(W \sim \mathrm{Beta}(\gamma, \delta+1)\), then
\(X = \{1 - [1 - W^{1/\lambda}]^{1/\beta}\}^{1/\alpha}\) follows the
GKw(\(\alpha, \beta, \gamma, \delta, \lambda\)) distribution.
For the BKw distribution, \(\lambda=1\). Therefore, the algorithm simplifies to:
Generate \(V \sim \mathrm{Beta}(\gamma, \delta+1)\) using
rbeta.Compute the BKw variate \(X = \{1 - (1 - V)^{1/\beta}\}^{1/\alpha}\).
This procedure is implemented efficiently, handling parameter recycling as needed.
References
Cordeiro, G. M., & de Castro, M. (2011). A new family of generalized distributions. Journal of Statistical Computation and Simulation, 81(7), 883-898. doi:10.1080/00949650903530745
Kumaraswamy, P. (1980). A generalized probability density function for double-bounded random processes. Journal of Hydrology, 46(1-2), 79-88. doi:10.1016/0022-1694(80)90036-0
Devroye, L. (1986). Non-Uniform Random Variate Generation. Springer-Verlag. (General methods for random variate generation).
Examples
set.seed(123)
x <- rbkw(1000, alpha = 2, beta = 3, gamma = 1.5, delta = 0.5)
summary(x)
#> Min. 1st Qu. Median Mean 3rd Qu. Max.
#> 0.04977 0.34173 0.45853 0.46130 0.57929 0.93144
## The sample follows the distribution
hist(x, breaks = 30, freq = FALSE, main = "")
curve(dbkw(x, alpha = 2, beta = 3, gamma = 1.5, delta = 0.5), add = TRUE)
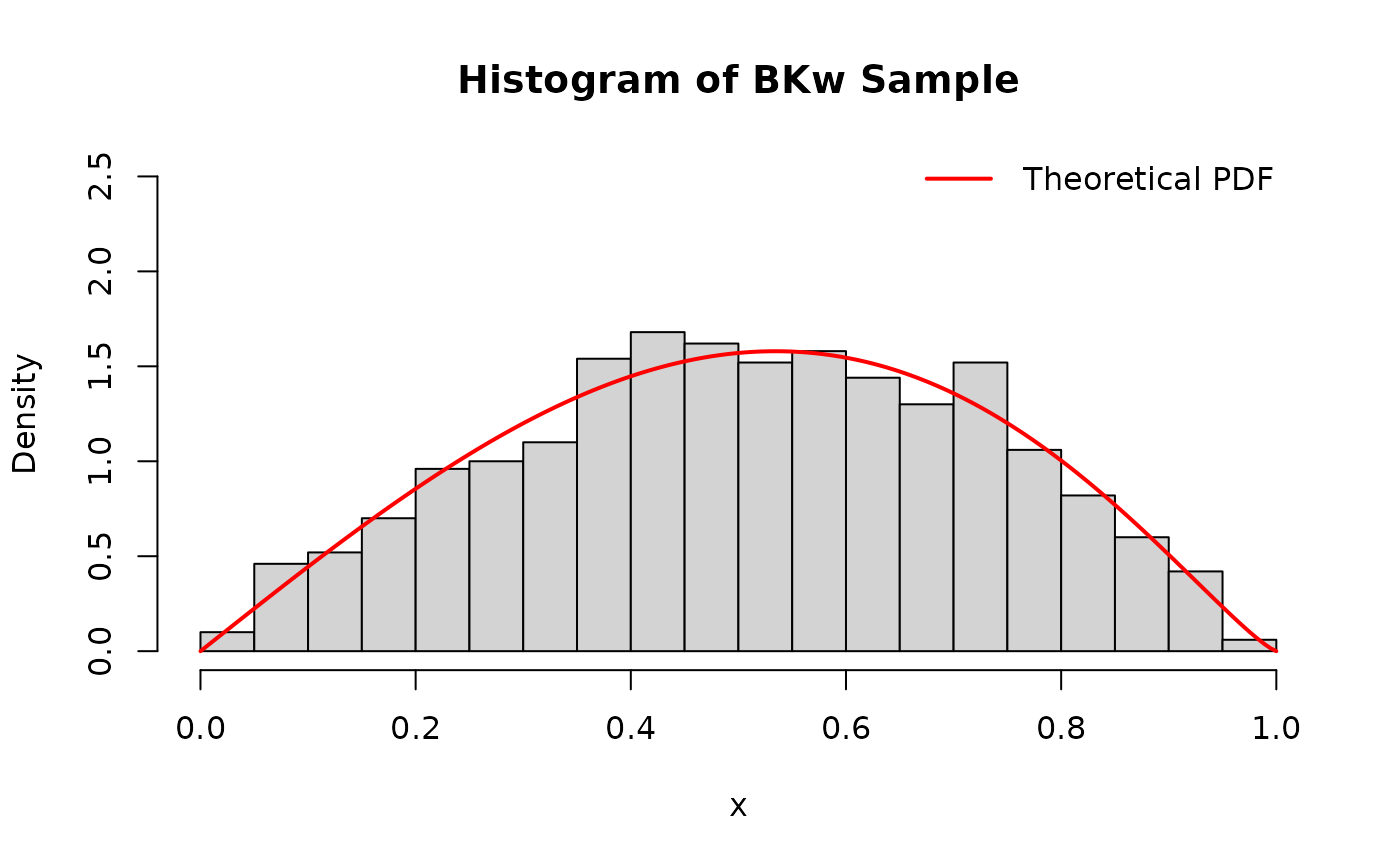 ks.test(x, pbkw, alpha = 2, beta = 3, gamma = 1.5, delta = 0.5)
#>
#> Asymptotic one-sample Kolmogorov-Smirnov test
#>
#> data: x
#> D = 0.024673, p-value = 0.5766
#> alternative hypothesis: two-sided
#>